Ripper payment methods: deposit versus withdrawal
Visa
- Deposit
- Yes
- Withdrawal
- Not listed
- Practical note
- Familiar card funding, but not shown as a cash-out rail.
Mastercard
- Deposit
- Yes
- Withdrawal
- Not listed
- Practical note
- Same asymmetry as Visa on the current banking page.
PayID
- Deposit
- Yes
- Withdrawal
- Not listed
- Practical note
- Account-to-account deposit option; not shown as a withdrawal method.
JetBank transfer
- Deposit
- Yes
- Withdrawal
- Not listed
- Practical note
- Deposit route distinct from standard bank-transfer withdrawal.
Bank transfer
- Deposit
- Not presented as a deposit route on the summary
- Withdrawal
- Yes
- Practical note
- Explicit withdrawal option on the current page.
eZeeWallet
- Deposit
- Yes
- Withdrawal
- Yes
- Practical note
- One of the few methods shown on both sides.
Bitcoin
- Deposit
- Yes
- Withdrawal
- Yes
- Practical note
- Crypto method shown for both deposits and withdrawals.
Bitcoin Cash
- Deposit
- Yes
- Withdrawal
- No
- Practical note
- Deposit supported; withdrawal not listed.
Lightning Bitcoin
- Deposit
- Yes
- Withdrawal
- No
- Practical note
- Deposit supported; withdrawal not listed.
Litecoin
- Deposit
- Yes
- Withdrawal
- No
- Practical note
- Deposit supported; withdrawal not listed.
Ether and Tether
- Deposit
- Yes
- Withdrawal
- Not listed
- Practical note
- Current page displays them as deposit options.
CashToCode / Neosurf
- Deposit
- Yes
- Withdrawal
- No
- Practical note
- Prepaid funding routes, not cash-out methods.
The table deliberately avoids exact processing-time and fee claims. Those details are more sensitive to method, account state and current cashier rules and belong in the dedicated Ripper withdrawals guide where they can be checked at page level.
The key banking lesson: choose an exit route before an entry route
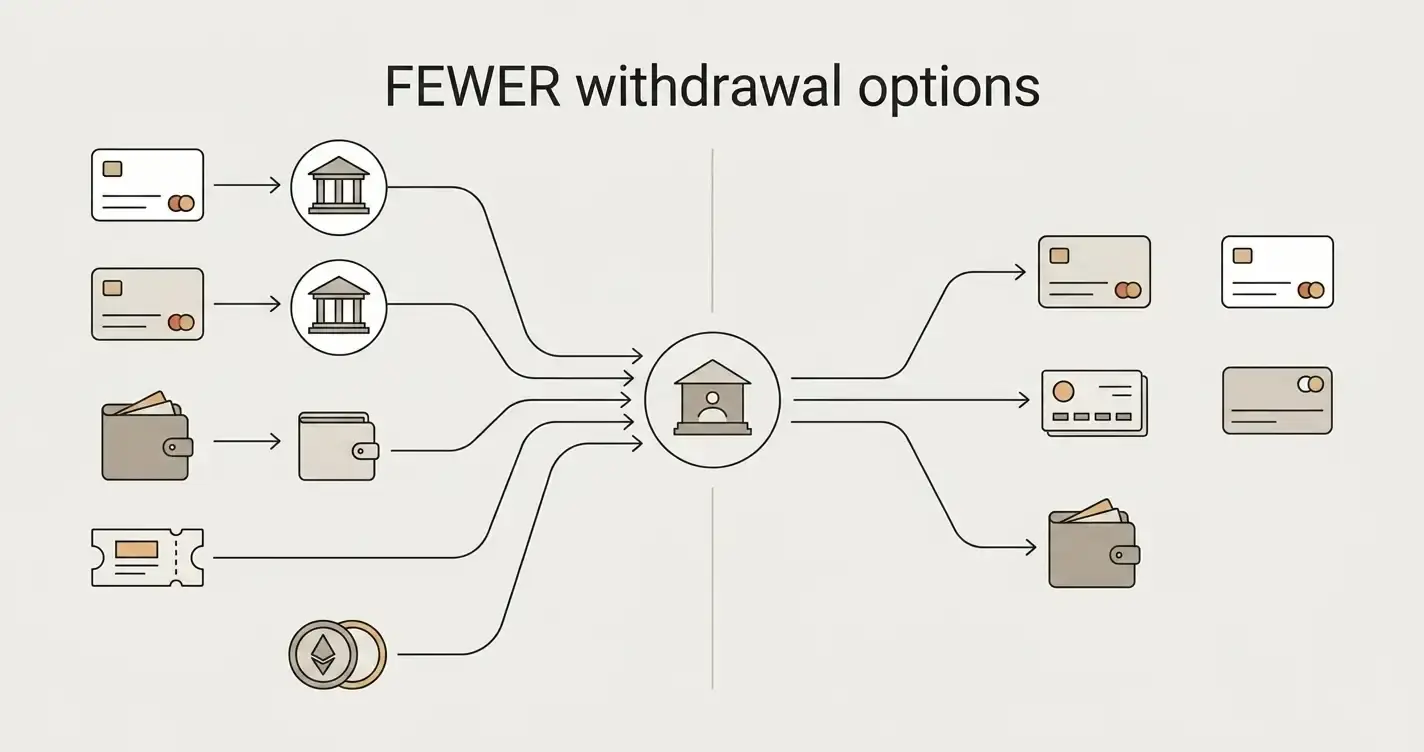
Casino banking pages often look generous because they display many logos, but deposit breadth can hide withdrawal concentration. Ripper is a clear example. Cards, vouchers, account-to-account options, an e-wallet and multiple crypto assets can fund play, yet the published withdrawal choices are much narrower.
That matters because a deposit method can be convenient at the start without being usable at cash-out. If you deposit by Visa, Mastercard, PayID, Neosurf or a crypto asset that is not withdrawal-enabled, the casino may need to route a future payout through a different eligible method. Ripper’s general terms say the casino retains discretion over withdrawal methods and that payments must be made to accounts owned and controlled by the user.
A practical banking decision therefore has two parts: first, can you fund the account in the way you want; second, do you already have access to a withdrawal rail the casino supports for your account? The second question is easier to overlook and usually more important.
Cards at Ripper and why they feel familiar in Australia
Ripper’s live banking page lists Visa and Mastercard as deposit methods. That matches a wider Australian payment environment in which cards remain dominant. The RBA’s 2025 Consumer Payments Survey found cards were used for about 73% of consumer payments, with debit cards alone accounting for roughly half of all payments.
That familiarity can reduce friction because users already understand card authorisation, account statements and mobile-wallet interfaces. It does not change the legal character of the merchant. Card availability should be read as a cashier feature, not as evidence of Australian approval.
It is also worth noting that Ripper’s current banking page does not mark Visa or Mastercard as withdrawal options. A player who deposits by card should therefore check the account cashier before assuming winnings can be returned to the same card.
PayID: locally familiar, but still just a Ripper deposit option
PayID is especially relevant to Australian readers because it is a familiar account-to-account payment mechanism. Ripper’s current banking page lists PayID as a deposit method. The RBA’s 2025 survey found adoption of account-to-account methods had increased strongly, particularly PayID, with around half of respondents reporting PayID use during the previous year.
That makes PayID recognisable to many Australians and potentially convenient for funding. However, Ripper does not currently list PayID as a withdrawal option on its banking summary. It also would be a mistake to treat PayID support as a regulatory signal. Payment infrastructure and gambling regulation answer different questions.
In other words, “supports an Australian payment habit” is not equivalent to “is an Australian-regulated gambling service.” For regulatory context, use the separate Australian regulatory status guide.
Vouchers: controlled funding with no matching cash-out path
CashToCode and Neosurf appear as deposit options on the current Ripper banking page. Prepaid vouchers can appeal to users who prefer to separate gambling spend from a primary bank card or who want a fixed funding amount.
The trade-off is one-way functionality. Neither voucher is shown as a withdrawal method. If you choose a voucher for budgeting convenience, decide in advance which supported withdrawal rail you could use later. A controlled deposit method is useful only if the eventual withdrawal path is equally clear.
eZeeWallet is one of the symmetrical options
eZeeWallet is currently listed for both deposits and withdrawals. That makes it structurally simpler than a card or voucher because the same category can potentially serve both directions.
Symmetry does not remove verification requirements or guarantee that every account will see identical limits. Ripper’s terms allow account checks and require payment methods to belong to the user. Still, from a planning perspective, a method that is explicitly supported on both sides reduces the need to switch rails later.
Crypto support is broad for deposits, narrower for withdrawals
Ripper’s banking pages list Bitcoin, Bitcoin Cash, Lightning Bitcoin, Litecoin, Ether and Tether among deposit options. This gives crypto users several ways to fund an account. The withdrawal summary, however, explicitly marks Bitcoin as available while several other crypto assets are shown as deposit-only or do not have a withdrawal option listed.
That asymmetry creates two practical risks. First, depositing one crypto asset does not guarantee you will be able to withdraw in the same asset. Second, moving between a casino balance and a different withdrawal rail can expose you to conversion, network or wallet-management considerations outside the casino itself.
For a user whose main reason for choosing crypto is end-to-end asset continuity, Bitcoin is the clearest currently published two-way option. Even then, confirm the live cashier at the moment of transaction because method availability can vary by account and can change.
What the RBA data adds to the decision
The RBA’s May 2026 analysis of the 2025 Consumer Payments Survey provides useful context for why some Ripper methods will feel more natural to Australian users. Cards remained the most common consumer payment method, accounting for around 73% of payments. Online payments represented about one-fifth of consumer payments, while account-to-account use continued to grow.
PayID is part of that account-to-account shift. Mobile-wallet use also increased, showing that Australians are increasingly comfortable with digital payment interfaces. These trends help explain user familiarity, but they should not be used to infer anything about the regulatory standing of a particular offshore gambling site.
The Australian wagering credit and digital-currency ban
ACMA states that from 11 June 2024, online and telephone wagering operators covered by the Australian credit ban cannot accept credit cards, funds linked to credit cards or digital currency for betting. The rule applies to online and telephone betting services, including on-course bookmakers.
This rule should not be misused as a shortcut for assessing Ripper. Ripper is an offshore online casino, while the ACMA credit-ban page describes payment restrictions applying to wagering services under the Australian framework. The fact that Ripper’s cashier lists cards or crypto does not prove Australian regulatory approval, and the Australian ban should not be repurposed as a claim that those Ripper cashier methods are validated or invalidated by local licensing.
The useful takeaway is narrower: Australian regulated wagering has specific payment restrictions, so a reader should not assume that a payment method common on an offshore casino maps neatly onto the rules governing locally regulated betting services.
Deposits and bonuses interact
Payment choice can affect bonus use because a promotion may require a minimum deposit or a particular code before the deposit is made. The current Ripper welcome package, for example, uses staged minimum deposits across four codes. A payment rail can also have its own minimum, so the amount needed to trigger a bonus is not always the only threshold that matters.
If you plan to use a promotion, check the Ripper bonuses guide before depositing. If you plan to test cash-out first, consider declining a bonus until you understand withdrawal conditions, because active promotional wagering can delay withdrawal eligibility.
Account ownership and verification
Ripper’s terms require payments to be made using accounts owned and controlled by the player. Withdrawals are subject to audit and identity verification. Those rules are relevant whichever payment method you choose.
A clean payment trail is therefore preferable: use your own card, bank account, wallet or crypto address where ownership can be demonstrated if requested, keep deposit records, and make sure registration details match the payment information. For the registration and verification workflow, see the account and KYC guide.
Which Ripper payment method is most practical?
There is no single best method for every Australian user, but the current cashier supports a few clear use cases:
- For familiar funding: Visa, Mastercard and PayID are recognisable options, but they are not shown as withdrawal rails.
- For fixed-budget deposits: CashToCode or Neosurf can separate gambling spend from a primary card, but you need another cash-out method.
- For a two-way digital wallet: eZeeWallet is explicitly listed for both deposits and withdrawals.
- For crypto continuity: Bitcoin is the clearest asset currently shown as both deposit and withdrawal capable.
- For a conventional payout route: bank transfer is explicitly listed for withdrawals.
The strongest decision rule is to pick the withdrawal route first. Once you know where a payout could go, choose the deposit method that gives you the best combination of convenience, budgeting control and bonus compatibility.
What to check in the live cashier
- Whether the method is visible for your specific logged-in account.
- Whether it is deposit-only, withdrawal-only or available in both directions.
- The current minimum and maximum transaction amounts.
- Any processing fee or network fee shown before confirmation.
- The expected processing stage and whether account verification is required first.
- Whether the payment account or wallet must match your registered identity.
- Whether an active bonus changes withdrawal eligibility.
Ripper’s public banking page is useful for planning, but the authenticated cashier is the last operational check before moving money.
Ripper banking FAQ
Does Ripper Casino accept PayID?
Yes. PayID is listed on the current Ripper banking page as a deposit option. It is not shown there as a withdrawal method.
Can I deposit with Visa or Mastercard?
Yes. Both are currently listed for deposits. The public banking summary does not list either card network for withdrawals.
Does Ripper support cryptocurrency?
Yes. The current banking page lists Bitcoin, Bitcoin Cash, Lightning Bitcoin, Litecoin, Ether and Tether for deposits. Bitcoin is explicitly shown as withdrawal-capable.
Which methods can be used for withdrawals?
The current public banking page explicitly marks Bitcoin, eZeeWallet and bank transfer as withdrawal methods. Availability can still depend on account status and the live cashier.
Does PayID support mean Ripper is Australian licensed?
No. PayID is a payment feature. It does not establish Australian licensing or regulatory approval.
Sources checked for this guide
Ripper-specific method availability was checked against the casino’s current banking page and terms on 27 August 2026. Australian payment behaviour comes from the Reserve Bank of Australia’s 2025 Consumer Payments Survey analysis. The wagering credit and digital-currency rule is described by ACMA’s credit-ban guidance.
For the complete evaluation beyond banking, return to the full Ripper review.
The full picture is in the Ripper Casino review for Australia.
Cashing out is covered separately under withdrawals.